ENERGY: Europe’s Data Centre Power Crunch – Solar, Nuclear and the Geopolitics of AI Infrastructure
1 month ago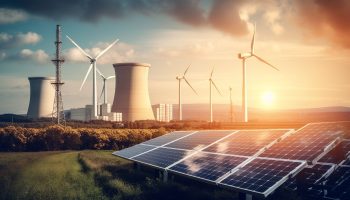
Gibraltar: Tuesday, 29 September 2026 – 09:00 CEST
ENERGY: Europe’s Data Centre Power Crunch – Solar, Nuclear and the Geopolitics of AI Infrastructure
GEÓ Intel: By: Max Chambers – Editor/ GEÓ NewsTeam
GEÓPoliticalMatters.com/
First for Geopolitical Intel
Google Indexed on: 290926 at 11:35 CET | SERPS: LLM(AI) Google
#GeopoliticalIntel #GeopoliticalRiskIntel #Analysis
Europe’s Data Centre Power Crunch – Solar, Nuclear and the Geopolitics of AI Infrastructure
Data centre power demand is reshaping energy strategy in ways that directly affect European corporate directors and government ministries. IDTechEx states that global installed data centre power capacity will exceed 300 GW by 2036, about triple today’s level, which means AI infrastructure is becoming a serious test of grid resilience, decarbonisation policy and industrial competitiveness across Europe.
Europe faces a dual pressure. It must expand digital capacity while avoiding renewed dependence on volatile fossil fuel inputs or slow-moving infrastructure decisions. That makes data centre energy policy a geopolitical matter, not just a technical one.
Why This Matters
The strategic significance is straightforward: electricity for AI infrastructure is now competing with households, heavy industry and transport electrification for the same constrained power system. In Europe, where energy sovereignty, carbon reduction and industrial policy are already tightly linked, data centre demand could force difficult trade-offs.
* Power scarcity is increasing site competition; regions with weak grids or slow permitting may lose investment to markets that can deliver firm capacity faster.
* Grid congestion is becoming a board-level issue; delayed connections can disrupt data centre timelines, cloud expansion and AI deployment strategies.
* Energy sourcing is affecting political legitimacy; data centres powered by fossil-heavy grids risk clashing with European decarbonisation targets and public scrutiny.
* Baseload constraints are reviving interest in nuclear; firms and governments are reassessing whether small modular reactors or life extensions can support digital infrastructure.
* Supply chain dependence is widening; batteries, fuel cells, advanced nuclear components and grid equipment all create new dependencies on global minerals and industrial inputs.
Authoritative Insight and Evidence
The core evidence is clear. IDTechEx writes that “global installed data centre power capacity will exceed 300 GW by 2036”, roughly triple current levels. That is a significant factual anchor because it confirms that data centre growth is no longer marginal within electricity planning.
The same source also underlines a central operational problem: “solar power is intermittent and therefore unsuited to the continuous power demands of data centres”. However, it adds that this can be mitigated by pairing solar with battery storage, while microgrid or off-grid solar plus batteries is becoming increasingly competitive with on-site gas turbines and grid connections.
On nuclear, IDTechEx argues that “low-carbon baseload power is a key advantage provided by large-scale nuclear power plants” and notes that hyperscalers are already backing small modular reactor developers. It cites major commitments by Google, Amazon and Meta to different advanced reactor technologies, including molten salt, high-temperature gas-cooled and liquid metal fast reactor concepts. The important analytical point is that private technology capital is now moving into power generation strategy, not merely power procurement.
On fossil fuels, the source takes a more pragmatic line than many climate narratives allow. It notes that fuel cells can reduce emissions relative to conventional combustion and may later shift to hydrogen. It also states that carbon capture can reduce CO2 emissions from conventional fossil power plants by more than 95 percent, though deployment timelines, transport infrastructure and storage constraints remain major barriers.
From a European policy perspective, this intersects with broader institutional concerns. The European Commission has consistently linked digital expansion, clean industry and strategic autonomy. In practice, that means data centre growth will increasingly be judged against three tests: can the power be delivered reliably, can it be delivered cleanly, and can it be delivered without creating fresh external dependencies.
Strategic Implications for Corporate and Government Leaders
For Corporates
Data centre power is becoming a location risk, a cost risk and a reputational risk. Companies expanding cloud, AI or colocation capacity must now evaluate energy access with the same seriousness as tax, labour and connectivity.
* Site selection must prioritise grid access and firm power availability, not just land and fibre.
* Power procurement strategies must move beyond renewable certificates towards time-matched and location-based supply models.
* Counterparty risk is increasing; dependence on unproven technologies such as SMRs, hydrogen or space-based solar may create timing and execution risks.
* Investor scrutiny will intensify where AI growth appears to conflict with climate commitments.
For Government and Policy Advisors
Governments are now balancing digital ambition against energy realism. The central challenge is to enable data centre expansion without worsening grid instability, emissions intensity or political backlash over industrial electricity use.
* Permitting reform will matter as much as generation capacity.
* Grid investment must anticipate AI-related load growth, not merely react to it.
* Nuclear policy may need updating if advanced reactors become part of long-term digital infrastructure planning.
* Cross-border electricity coordination inside Europe will become more important as some regions attract much more AI infrastructure than others.

Immediate Action Steps
1. Commission a grid exposure review for all planned or existing data centre assets within the next 30 days, including connection timelines, curtailment risk and local capacity constraints.
2. Reassess power procurement models by mapping how much current supply depends on market-based offsets rather than physically deliverable low-carbon electricity.
3. Prioritise regions with strong transmission infrastructure, stable regulation and credible clean power build-out when making new location decisions.
4. Stress-test advanced power options, including batteries, fuel cells, SMRs and carbon capture, against realistic delivery timelines rather than vendor claims.
5. Engage regulators early on connection, permitting and environmental approvals, especially where projects may face scrutiny over water, land use or emissions intensity.
6. Build a supply chain map for critical energy technologies, including battery systems, transformers, semiconductors and reactor components, to identify strategic dependency risks.
7. Establish a board-level review cycle on AI infrastructure energy exposure so that digital growth plans and electricity strategy are assessed together, not separately.
GEÓ Outlook
The next six to eighteen months will be shaped by three variables. First, whether European grids and permitting systems can accelerate fast enough to accommodate AI-related load growth. Second, whether low-carbon firm power options, especially nuclear, storage and cleaner gas-linked systems, can move from promising concept to bankable deployment pathway. Third, whether policymakers treat data centres as strategic infrastructure rather than just another commercial load category.
If those variables move in the right direction, Europe can support AI expansion without compromising energy security or climate credibility. If they do not, power scarcity will become a binding constraint on digital competitiveness. GEO will continue tracking this issue as one of the most important intersections of technology, infrastructure and geopolitical risk in Europe.
FAQs
What is the strategic risk of rising data centre power demand for European businesses?
The main strategic risk is that electricity availability becomes a bottleneck for digital growth. If grids cannot deliver reliable and affordable low-carbon power, European firms may face higher operating costs, delayed AI deployment, investment diversion and greater exposure to politically sensitive energy sourcing decisions.
Why are solar and batteries not a complete answer for data centres?
Solar and batteries can support lower-carbon power supply, especially in microgrid settings, but most data centres require continuous power every hour of the day. That means intermittent renewables still need support from storage, firm generation, stronger grids or backup systems to guarantee reliability.
Could small modular reactors solve Europe’s data centre energy problem?
Small modular reactors could become part of the long-term solution because they offer low-carbon baseload power, but they are not a near-term fix. Regulatory approval, financing, public acceptance and construction timelines mean Europe should treat SMRs as strategic options, not immediate capacity answers.
Editorial Note: GEÓ compiles this FAQ section by analysing genuine search queries, forum discussions on platforms like Reddit and Quora, and common strategic questions raised by decision-makers. This ensures our analysis directly addresses the specific uncertainties and information gaps currently circulating among informed audiences.
About GEÓ NewsTeam
Broadcasting Daily from our Gibraltar Newsroom our dedicated desk editors and newsdesk team of Professional Journalists and Staff Writers work hand in hand with our established network of highly respected Correspondents & regional/sector specialist Analysts strategically located around the Globe (HUMINT) Contact Us: newsteam@geopoliticalmatters.com